Healthcare Cost & Medical Tourism Estimator
Select your location to see estimated financial impacts based on CMS and Kaiser Family Foundation data trends.
State Comparison Data
| Metric | Hawaii | Massachusetts | US Average |
|---|---|---|---|
| Avg. Monthly Health Premium (Family) | $680+ | $720+ | $610 |
| Cost of Living Index | 196 (Very High) | 148 (High) | 100 (Baseline) |
| Primary Financial Stressor | Inflation & Supply Chain | Billing Complexity & Specialist Fees | General Wage Stagnation |
You check your bank account after paying rent, groceries, and that shockingly high premium for your health plan. The number staring back isn't just low; it's scary. You aren't alone. When we talk about the hardest state to live in financially, we aren't just talking about expensive coffee or high rents. We are talking about the crushing weight of healthcare costs that can bankrupt a family even when they have a good job.
Most lists point to Hawaii or California because of housing. But if you dig into the data from the Centers for Medicare & Medicaid Services (CMS) and the Kaiser Family Foundation, a different picture emerges. The financial pain often comes from where you get sick, not just where you sleep. For millions of Americans, the "cost" of living is directly tied to the price of staying alive. This reality has pushed many to look beyond their borders, turning to medical tourism as a survival strategy rather than a luxury.
Hawaii vs. Massachusetts: The High Cost of Care
Why do experts often cite Hawaii as the hardest state financially? It’s a perfect storm. First, everything is imported. That avocado at the grocery store traveled thousands of miles, and you paid for every mile. Second, the population is older, which drives up demand for complex medical services. Third, the labor market is tight, keeping wages relatively low compared to the sky-high cost of living index.
But there is a counter-argument. Massachusetts consistently ranks near the top for healthcare spending per capita. In 2024, average annual healthcare spending in Massachusetts hovered around $13,000 per person, significantly higher than the national average of roughly $12,500. While residents have better access to care due to universal coverage mandates, the out-of-pocket costs for deductibles and specialist visits remain brutal for middle-income families.
The difference lies in the structure. Hawaii hurts you with daily inflation and limited supply chains. Massachusetts hurts you with the sheer volume and complexity of its medical billing systems. If you have chronic conditions like diabetes or heart disease, Massachusetts might feel harder because the specialized care you need is priced at a premium that insurance doesn't fully cover.
| Metric | Hawaii | Massachusetts | US Average |
|---|---|---|---|
| Avg. Monthly Health Premium (Family) | $680+ | $720+ | $610 |
| Cost of Living Index | 196 (Very High) | 148 (High) | 100 (Baseline) |
| Uninsured Rate | ~5% | <3% | ~8% |
| Median Household Income | $94,000 | $96,000 | $74,000 |
The Hidden Killer: Out-of-Pocket Maximums
Here is the part most people miss. Your monthly premium is just the entry fee. The real financial danger is the out-of-pocket maximum. This is the cap on what you pay before insurance takes over completely. In high-cost states, this number can hit $9,000 to $10,000 for an individual.
Imagine you need a knee replacement. In a standard plan, you might pay $3,000 upfront for consultations, imaging, and physical therapy before surgery. Then, during the procedure, facility fees, anesthesia, and surgeon fees add up. If your deductible hasn't been met, you are paying cash rates. These rates are often 300% higher than negotiated insurance rates. One bad diagnosis can wipe out a year's savings in states with high provider consolidation, where hospitals have little competition to lower prices.
This isn't just theoretical. A 2023 study by the Commonwealth Fund found that nearly 40% of adults in high-spending states reported problems paying medical bills in the past year. That includes skipping prescriptions or delaying necessary procedures because they couldn't afford the copay. When you delay care, small issues become big, expensive emergencies. It’s a vicious cycle that traps people in debt.
Why Insurance Doesn't Always Save You
You might think, "I have great insurance." But have you read the fine print? Network adequacy is a major issue in rural areas of states like Texas and Florida. You might have a PPO plan, but the nearest specialist who accepts it is three hours away. Do you take unpaid time off work? Pay for gas and tolls? Hire a sitter?
These hidden costs add up. Moreover, surprise billing remains a problem despite federal protections. Anesthesiologists, radiologists, and pathologists often work independently within hospital networks. They might be out-of-network even if your hospital is in-network. In states with weaker balance-billing laws, you could receive a bill for thousands of dollars after a routine emergency room visit.
Furthermore, the administrative burden is heavy. Navigating prior authorizations requires phone calls, faxes, and follow-ups. For hourly workers, this means lost wages. For salaried employees, it means stress and burnout. The financial toll isn't just monetary; it's temporal. Time spent fighting insurance companies is time not earning money or resting.
Medical Tourism: The Escape Hatch
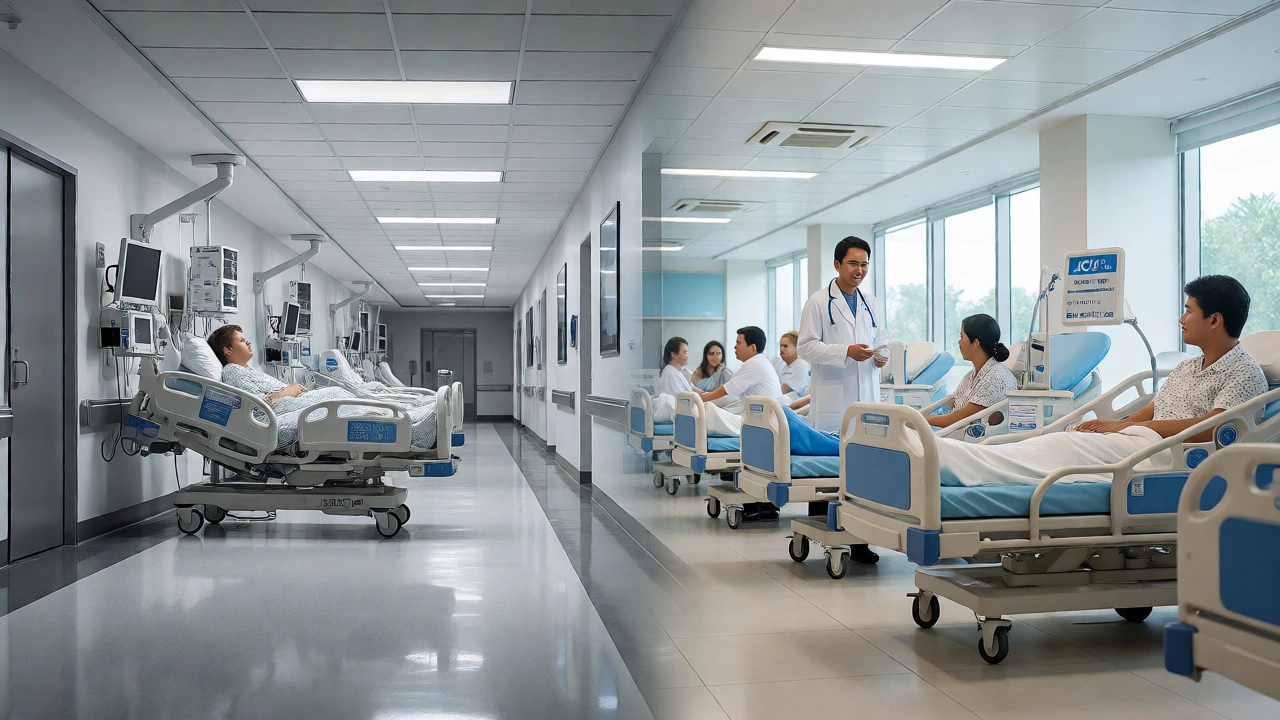
This is where medical tourism shifts from a niche trend to a practical financial tool. When domestic costs become unsustainable, patients look abroad. Countries like India, Thailand, Turkey, and Mexico offer high-quality care at a fraction of US prices.
Let’s look at a concrete example. A total hip replacement in the United States averages between $30,000 and $50,000. After deductibles and coinsurance, a patient might still owe $5,000 to $10,000 out of pocket. In India, the same procedure at a JCI-accredited hospital costs between $4,000 and $6,000. Even including round-trip flights and two weeks of accommodation, the total cost rarely exceeds $8,000.
That’s a savings of up to 80%. For someone without insurance or with a high-deductible plan, this difference is life-changing. It allows them to fix a health issue without selling assets or going into debt. It’s not just about cheaper surgeries; it’s about accessible diagnostics. An MRI in the US can cost $1,000 to $2,000. In many medical tourism hubs, it’s $100 to $200.
Is Medical Tourism Right for You?
It’s not a one-size-fits-all solution. You need to weigh the risks against the rewards. Here is a quick decision framework:
- Elective Procedures: Best candidates are those needing dental implants, cosmetic surgery, orthopedics, or fertility treatments. These are planned events where you can schedule recovery time.
- Complex Cases: If you have multiple comorbidities, ensure the foreign hospital has robust intensive care units and English-speaking staff.
- Follow-up Care: Can you manage post-op care locally? Some surgeons require frequent visits. Telemedicine has made remote follow-ups easier, but physical exams may still be needed.
- Insurance Coverage: Most US insurers won’t cover overseas treatment. You must pay upfront. However, some flexible spending accounts (FSAs) allow reimbursement for qualified medical expenses abroad. Check with your provider.
Don’t go blindly. Look for hospitals accredited by international bodies like the Joint Commission International (JCI). These accreditations mean the facility meets global safety standards, similar to those in the US. Read reviews from other patients, specifically those who had similar procedures. Ask about complication rates. Reputable clinics will provide transparent data.
Beyond Surgery: Dental and Fertility Savings
While surgeries get the headlines, dental and fertility treatments are massive drivers of medical tourism. Dental work is rarely covered by standard health insurance in the US. A single crown can cost $1,500. A full set of veneers can run $20,000. In Costa Rica or Hungary, these costs drop by 60-70%. Many people combine a vacation with a week of dental work, returning home with a new smile and their savings intact.
Fertility treatments, such as IVF, are another area where costs skyrocket. A single IVF cycle in the US averages $12,000 to $15,000, excluding medication. In countries like India or Czech Republic, the same cycle costs $3,000 to $5,000. For couples struggling to conceive, the ability to try multiple cycles without financial ruin makes medical tourism a beacon of hope.
Which state is truly the most expensive for healthcare?
While rankings vary by year, Hawaii and Massachusetts consistently top the list for overall cost of living and healthcare spending. However, states like West Virginia and Mississippi often rank highest for uninsured rates and poor health outcomes, creating a different type of financial hardship due to lack of access rather than just high prices.
Does my US health insurance cover medical tourism?
Generally, no. Most private US health insurance plans do not cover elective procedures performed abroad. Some employer-sponsored plans or specific travel insurance policies might offer partial coverage or reimbursement, but you usually need to pay out-of-pocket and file claims manually. Always verify with your insurer before booking.
Is medical tourism safe?
Yes, provided you choose accredited facilities. Look for Joint Commission International (JCI) accreditation, which ensures hospitals meet rigorous international safety and quality standards. Research the surgeon’s credentials, ask about infection rates, and ensure there is a clear protocol for handling complications.
What are the hidden costs of medical tourism?
Beyond the procedure cost, consider airfare, accommodation, meals, local transportation, and visa fees. Also, factor in lost wages during travel and recovery. If complications arise, you may need extended stays or additional treatments, which can increase costs. Budget for 10-20% extra for contingencies.
How far in advance should I plan a medical trip?
Start planning 3-6 months in advance. This allows time for virtual consultations with foreign doctors, obtaining medical records, arranging visas, and scheduling flights. Rushing can lead to inadequate preparation and increased risk.
Final Thoughts: Taking Control of Your Health Wallet
Living in a high-cost state doesn't have to mean sacrificing your health or your future. Understanding where your money goes-whether it's inflated premiums in Hawaii or complex billing in Massachusetts-is the first step. The second step is exploring alternatives. Medical tourism isn't about flying across the world for a bandage; it's about strategic healthcare management. By comparing options and looking beyond local borders, you can find care that fits both your body and your budget.